Investments · Strategic deductions
Sheet A-105 · Details
§ 01 · Strategic Deductions
You can’t deduct your salary.You can deduct what it buys.
Congress wants more energy, more equipment, more working businesses. So it gives a tax benefit to whoever pays for them. Most people who use these rules own companies. This is the one place where business owners and wage earners play by the same rules.
Detail 01 · Leveraged deductions
A business that borrows.
You put money into a business and you work in it. The business borrows to buy what it needs. Your deductions come from everything the loan buys, not just what you put in. So each dollar you invest can bring more than a dollar of deductions.
Detail 02 · Energy
A well, written off up front.
Most of what it costs to drill a well is deductible the year it’s drilled. A working interest means you own part of the well and pay your share of drilling and running it, not just collect from it. Owned that way, the deduction can count against your salary.
Detail 03 · Tax-aware funds
Losses you can use.
A fund that owns some stocks and bets against others, built to produce losses along the way. You use those losses against gains, like the gain when you sell company stock. Some versions are built for ordinary income instead.
The test. Would you own this if the tax benefit didn’t exist? That’s the first question we ask. If the deduction is the only reason to own it, it doesn’t belong in a portfolio.
Here’s the tradeoff
- T1Leveraged deductions require material participation: real hours in the business, tracked and written down.
- T2The debt is real, and you’re personally on the hook. That’s what makes it count. It also makes losses bigger.
- T3There’s a yearly cap on how much of these losses can count against a salary. What’s over it isn’t lost. It carries forward and can offset up to 80% of your taxable income in later years, which for high earners can be worth more than the first-year deduction.
- T4If a leveraged deal loses money, the deduction can still be worth more than you put in. Not every deal works that way, and we only go into a deal we expect to make money.
- T5Most tie your money up for years. Some leveraged deals can be sold sooner, but part of the deductions gets taxed back when you do.
- T6You have to qualify, usually by income or net worth. Some set the bar higher.
- T7How much you can use depends on your income, your state and the rest of your return.
For illustration only. Not a projection, an offer or a recommendation. Private investments are illiquid, can lose value and are available only to qualified investors. Tax treatment depends on your situation.
Sheet A-201 · Specification
§ 02 · The Analysis
You’ll finally know.What your portfolio costs you.
A portfolio costs you in three ways. Tax on what it earns, fees to hold it, and the return you give up because of where things sit. Two of those show up somewhere. The third one never does.
It's a written deliverable, not a sales call. We read every account as one portfolio, through both an investment lens and a tax lens, and we put all three costs in writing. It's a paid piece of work, and it stands on its own. Some people take it and act on it themselves. If you want us to do the work, we manage the portfolio from there, and the structural work that goes with it is part of managing the money.
Schedule · What you leave with
- 01What you actually own. Every account read as one portfolio instead of a drawer of statements. What you hold, where you hold it, and what it costs you to hold it there.
- 02Where each dollar should sit. Asset geography, account by account, against where it sits today.
- 03Where the two collide. The places your investments and your tax situation work against each other, and where after-tax return is being left on the table.
- 04What we'd change. Specific recommendations, ranked in order, with enough detail that you could act on them without us.
The first step is a 30-minute call to see whether the analysis fits your situation.
Sheet A-900 · Stamp Block
§ 03 · The Principals
The people who do the work.One for investments. One for tax.
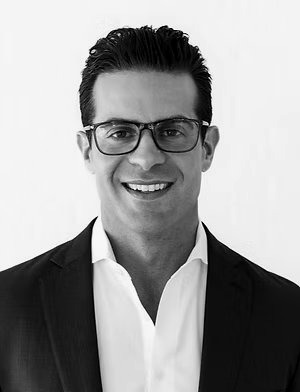
Shaun Eck
Managing Partner · Co-FounderCame from Merrill Lynch and a family office. Runs the investment side.
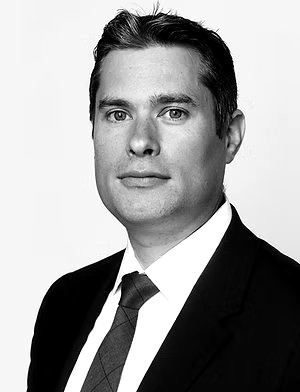
Jordan Frenkel, CPA, MBA
Managing Partner · Co-FounderCame from PwC, hedge funds and Guggenheim Partners. Runs the tax side.
Sheet A-100 · Index
Next step
Next Step
Book a 30-minute call.
We'll figure out whether working together is the right next step for your situation. No sales pitch, no follow-up sequence. Thirty minutes with Shaun and Jordan.